Rental Invoice for Businesses: VAT, Monthly Billing and What Your Accountant Needs
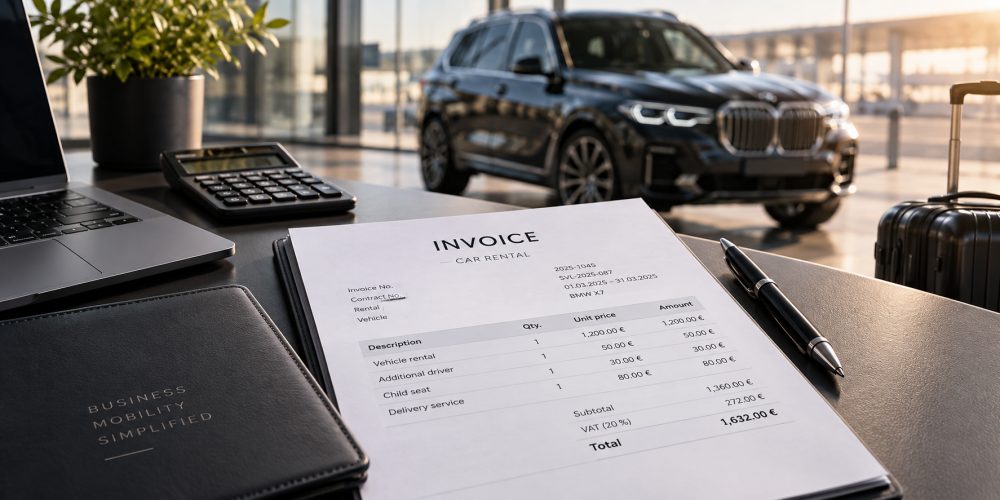
A rental invoice includes a breakdown of the rental and any additional charges, VAT and payment details. For long-term rentals, billing can be arranged on a monthly basis. When renting to a business in another EU country, the reverse-charge mechanism may apply. And what about the deposit? A standard refundable deposit is not treated as payment for the rental itself.
An accountant doesn’t need a story about how comfortable the car was. They need a document that can be processed without a phone call. Correct details, a clear breakdown and the right VAT information.
For a business car rental, the invoice should therefore be easy to check and easy to account for. Here is what you should find on it, how invoicing works for long-term rentals and what to keep in mind when it comes to VAT.
What does a car rental invoice include?
The main item is the vehicle rental for the agreed rental period. The invoice should clearly state the vehicle, rental period and contract number.
If you have ordered additional services, they should be listed as separate items. These may include:
- an additional driver,
- a child seat,
- vehicle delivery or collection,
- a fee related to travelling abroad,
- a chauffeur service.
Not all costs are necessarily known when the initial invoice is issued. After the vehicle is returned, a separate invoice may therefore be issued for items such as excess mileage, missing fuel or damage costs, if applicable under the rental agreement.
How is the payment shown?
The invoice also states the payment method. If you paid by card or cash, it is clear that the amount was settled directly during the rental.
On a standard rental the rent is paid in advance, within 24 hours of booking (otherwise the booking is cancelled automatically) — by bank transfer with the variable symbol from the payment details as the payment reference, or by card online where offered — and the invoice carries the same reference, so your accountant can match the payment easily. With monthly invoicing, the invoice includes the information required for payment, such as the payment reference and due date.
It may seem like a small detail, but it can save your accountant unnecessary time when matching payments.
All documents in one place
A business rental involves more than just an invoice. You may also have the rental agreement, any amendments and vehicle handover and return reports.
When these documents are available electronically, you can simply send the relevant PDF to your accountant or give them access to your customer account. There is no need to search through old emails for individual documents.
VAT on business car rentals
For a business vehicle rental, it is important to consider how the vehicle is used and which VAT rules apply to the specific service.
If your company is VAT registered, the right to deduct VAT depends on the applicable VAT rules and on the actual use of the vehicle. The situation may be different when a vehicle is used exclusively for business purposes compared with a vehicle that is also used privately.
The specific assessment should therefore be made by your accountant or tax adviser. They know how your company actually uses the vehicle and can determine the applicable VAT treatment.
For companies based abroad, the place of supply and the applicable VAT regime must also be considered. This is why it is best to provide the correct billing details and VAT number when making the reservation.
A security deposit is not a rental payment
A security deposit is a separate matter.
It is not payment for the rental of the vehicle or for another service. It is therefore normally not invoiced as a taxable supply. After the rental ends, the deposit is returned according to the rental conditions or may be used to cover eligible costs where applicable.
If your accountant is looking for an invoice for the deposit, it is important to distinguish between payment for a service and a refundable security deposit.
The specific accounting treatment of the deposit depends on the accounting rules and your company’s accounting setup, so it should be handled with your accountant.
Long-term rental and monthly invoicing
For a rental lasting several months, receiving one large invoice for the entire rental period may not always be practical.
With long-term rentals, the rental can therefore be invoiced period by period. This gives you a document for each relevant period and means your accounting team does not have to allocate one large expense across several months.
If the rental starts or ends in the middle of a month, the amount for that period may be calculated proportionally according to the agreed rental conditions.
The result is a clearer overview of costs and better cash-flow management.
When the car is rented by a company from another country
For a foreign company, it is important to know who the customer is, where the company is established and what type of rental is involved.
For cross-border rentals, there is no single universal VAT rule that applies in every situation. Specific rules can apply to the rental of means of transport depending on the rental period and type of customer.
For this reason, it is best to provide the billing details and a valid VAT number before the invoice is issued. This allows the correct VAT treatment to be determined from the start.
Who signs the rental agreement?
The invoice and rental agreement should contain the correct details of the same company.
The agreement is therefore signed on behalf of the company by a person authorised to act for it, typically a managing director or another authorised representative.
If employees will regularly collect vehicles, it is practical to arrange the necessary authorisation in advance. This means the managing director does not have to deal with every individual rental or vehicle collection.
When the entire process is handled electronically, agreements, amendments and other documents can be completed without a printer or courier.
Example
A company rents a seven-seat SUV for four months. The vehicle will be used by the managing director and two employees.
The rental is invoiced monthly. The invoice states the rental period and the vehicle rental price. If an additional charge arises during a particular period, such as excess mileage, it is listed separately according to the rental agreement.
A security deposit was paid at the beginning of the rental as a refundable deposit. After the rental ends and all outstanding amounts have been settled, it is returned according to the agreed conditions.
The accountant therefore receives a clear document for each rental period and has the complete documentation at the end of the rental.
That is exactly what a business rental should achieve: an invoice that does not need an explanation.